By Brandon Miller—
I’ve spent a lot of years sitting across the table from people right as their relationship is ending. No two situations ever look the same. But here’s something I’ve learned that holds true across all of them: a lot is going to feel outside of your control. What isn’t is how you choose to move through it. That tends to dictate how you walk away in the end.
Separating your finances is one of those things. Handled well, you both walk away with your sanity intact, sometimes even as friends. Handled poorly, it turns into resentment and bickering that could have been avoided entirely. The difference comes down to how you choose to go forward. It doesn’t have to be as ugly as it feels right now, and getting started is a lot easier than most people realize.
Separate cash flow first.
Before anything else, separate your cash flow. This is the one move that shouldn’t wait on lawyers, mediators, or even a final decision about where things are headed. You don’t need to see what your ex has been up to. Watching their spending come through a shared account doesn’t give you anything useful; it just breeds resentment. Open your own checking account and card. That’s it; that’s the first step, and everything else can follow once that’s done. Of course, how much untangling comes next depends on your degree of overlap; whether you kept completely separate accounts or merged every dollar shapes what that looks like.
Not all dollars are created equal.
From there, the numbers themselves need just as much attention as the accounts do. A million dollars in a Roth account is not the same as a million dollars in a traditional IRA once taxes enter the picture, and neither is the same as a million dollars of home equity. I always push for a fair split that accounts for after-tax value, factoring in cost basis and capital gains, not just the balance on a statement. Divide assets without doing that math, and one person can walk away with significantly less than it looks like on paper.
Watch out for emotional decisions.
Once the numbers are sorted, the harder work is usually emotional. I see it often: fighting to keep the family home can feel like a win, but it isn’t one if it leaves you with no liquidity to actually live your life. And minimizing your own spending during a split, whether out of guilt, frugality, or wanting to seem like the bigger person, can quietly work against you, since your standard of living during this period often factors into how support gets calculated. My advice is always to handle these decisions with clear eyes, not emotion.
Bring in a neutral third party.
This last piece matters so much. You don’t need a courtroom to benefit from it. I walk both people through the math together, translate what “even” actually means in after-tax terms, and keep the conversation on numbers instead of history. If you’re going to be mad at someone in this process, be mad at the mediator, not each other. That’s not a joke; it’s strategy, and it’s often how the relationship survives the split intact.
It’s worth remembering that, at some point, you loved this person. Solving the money puzzle early gives you both a real shot at keeping that, and your sanity, along the way. If you’re working through your own version of this, a breakup, a separation, or a divorce, we would love to help you make sense of things.
Book a complimentary Make It Happen meeting to learn more: https://bit.ly/3VHosvr
This material presented by Brio Financial Group (“Brio”) is for informational purposes only and is not intended to serve as a substitute for personalized investment advice or as a recommendation or solicitation of any particular security, strategy, or investment product. Facts presented have been obtained from sources believed to be reliable, however, Brio cannot guarantee the accuracy or completeness of such information, and certain information presented here may have been condensed or summarized from its original source. This information may contain certain statements that may be deemed forward-looking statements. Please note that any such statements are not guarantees of any future performance, and actual results or developments may differ materially from those discussed. No investor should assume future performance will be profitable or equal the previous reflected performance. Any reference to an index is included for illustrative purposes only, as an index is not a security in which an investment can be made. They are unmanaged vehicles that serve as market indicators and do not account for the deduction of management fees and/or transaction costs generally associated with investable products. The S&P 500 Total Return Index represents U.S. stock returns. This includes 500 leading companies in the U.S. and is widely regarded as the best single gauge of large-cap U.S. equities, where dividends are reinvested. The holdings and performance of Brio client accounts may vary widely from those of the presented indices. Brio does not provide legal or tax advice, and nothing contained in these materials should be taken as legal or tax advice. Advisory services are only offered to clients or prospective clients where Brio and its representatives are properly licensed or exempt from licensure. No advice may be rendered by Brio Financial Group unless a client service agreement is in place. For more information about our advisory services and fees, please refer to our ADV brochure found at https://adviserinfo.sec.gov/
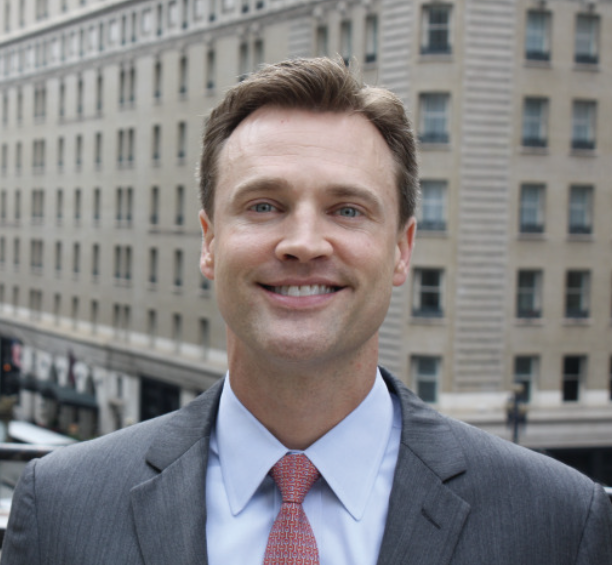
Brandon Miller, CFP®, is a financial consultant at Brio Financial Group in San Francisco, specializing in helping LGBT individuals and families plan and achieve their financial goals. For more information:
https://www.briofg.com/
Money Matters
Published on September 24, 2026


Recent Comments